The Difference Between Equity and Cash
Real Amigos Team · March 7, 2026 · 8 min read
The Great Misunderstanding: Equity is Not Cash
It’s a phrase you hear all the time in real estate forums and from friends who just bought a place: “I have $80,000 in equity.” This statement, while potentially true, is one of the most misunderstood concepts in property ownership. The confusion is understandable. In most financial contexts, a number on a page represents a tangible amount of money you can access. Your bank statement shows a balance, and you can withdraw that amount. Your investment portfolio has a value, and you can liquidate stocks to get cash. But with property, the word equity operates differently, and this distinction is critical for co-owners to grasp.
The fundamental difference is this: equity is the portion of your property you truly own, calculated as the home's current market value minus any outstanding mortgage or loan balances. It’s a measure of your ownership stake. Cash, on the other hand, is liquid money in your bank account—funds you can use for daily expenses, investments, or anything else. You cannot walk into a grocery store and buy food with your home equity. This might seem obvious, but the language we use around equity often blurs the line, leading to significant financial miscalculations and disagreements between co-owners.
Why We Confuse Them: The Illusion of Wealth
The confusion between equity and cash often starts with how we talk about it. When someone like your friend, let's call her Maria, says she has "$80,000 in equity," it sounds like she's sitting on a pile of money. It feels like a measure of wealth, and in a way, it is. But it's illiquid wealth. That $80,000 is locked within the physical asset of her home. It’s a number on paper, a reflection of her investment's performance, not a spendable balance.
 Equity is wealth — but it's locked inside an illiquid asset. The number on paper is not money in the bank.
This illusion can create false expectations. A common sentiment seen on forums like Reddit is from co-owners who feel "house rich, cash poor." They see their equity grow and assume they have a financial cushion, but when an unexpected expense arises, they find themselves unable to pay for it. This is because equity is not a savings account. Accessing its value is a complex process that involves specific financial maneuvers, each with its own costs and consequences.
How Equity Changes: The Ebb and Flow of Ownership
Understanding that equity is not cash is the first step. The next is realizing that equity is not a static number. It is constantly changing, influenced by several factors that can either increase or decrease your stake.
How Equity Grows
There are three primary ways your equity in a property increases over time. First, every mortgage payment you make includes a portion that pays down the principal—the original loan amount. As you reduce what you owe, your ownership stake naturally grows. This is the most predictable path to building equity. Second, property appreciation can significantly boost your equity. If the market value of your home increases due to demand, location, or other economic factors, your equity grows with it. Finally, as discussed in our "The Hidden Truth About Capital Improvements" article, making capital improvements like renovating a kitchen or adding a bathroom can also increase your home's value and, therefore, your equity.
How Equity Can Shrink
Just as equity can grow, it can also shrink. A market downturn can cause your property’s value to decrease, taking your equity down with it. Furthermore, the value of capital improvements depreciates over time; a new roof that added $20,000 in value on day one may only be worth a fraction of that a decade later. Lastly, taking on more debt against the property, such as through a home equity line of credit (HELOC), directly reduces your equity because it increases the amount you owe.
The Co-Owner's Dilemma: "I Want My Equity"
This brings us to a critical point for co-owners. When one partner, let’s call him David, says, “I want my equity out of the house,” he is almost never asking for a revised statement of his ownership stake. He is asking for cash. This is where the conversation can become difficult. If David has $80,000 in equity, his co-owner, Sarah, might not have $80,000 in cash to simply hand over. The equity is tied up in the property they own together.
To unlock that equity and turn it into cash, they have three main options:
- Sell the Property: This is the most straightforward way to access equity. Once the home is sold, the mortgage is paid off, closing costs are covered, and the remaining cash is distributed among the co-owners according to their ownership shares.
- Refinance the Mortgage: Sarah could refinance the mortgage, taking out a larger loan to cash out David’s share. This would leave her as the sole owner but with a higher mortgage balance.
- Home Equity Line of Credit (HELOC): The co-owners could take out a HELOC to access a portion of their equity. However, this adds a new monthly payment and increases their total debt.
Each of these options has significant financial implications, and none of them are as simple as withdrawing money from a bank.
The Buyout Math: From Equity to Actual Cash
Let’s return to David’s $80,000 in equity. If he and Sarah decide to sell the house to give him his cash, the final amount he receives will be different from that initial equity figure. The buyout math is not a simple one-to-one conversion.
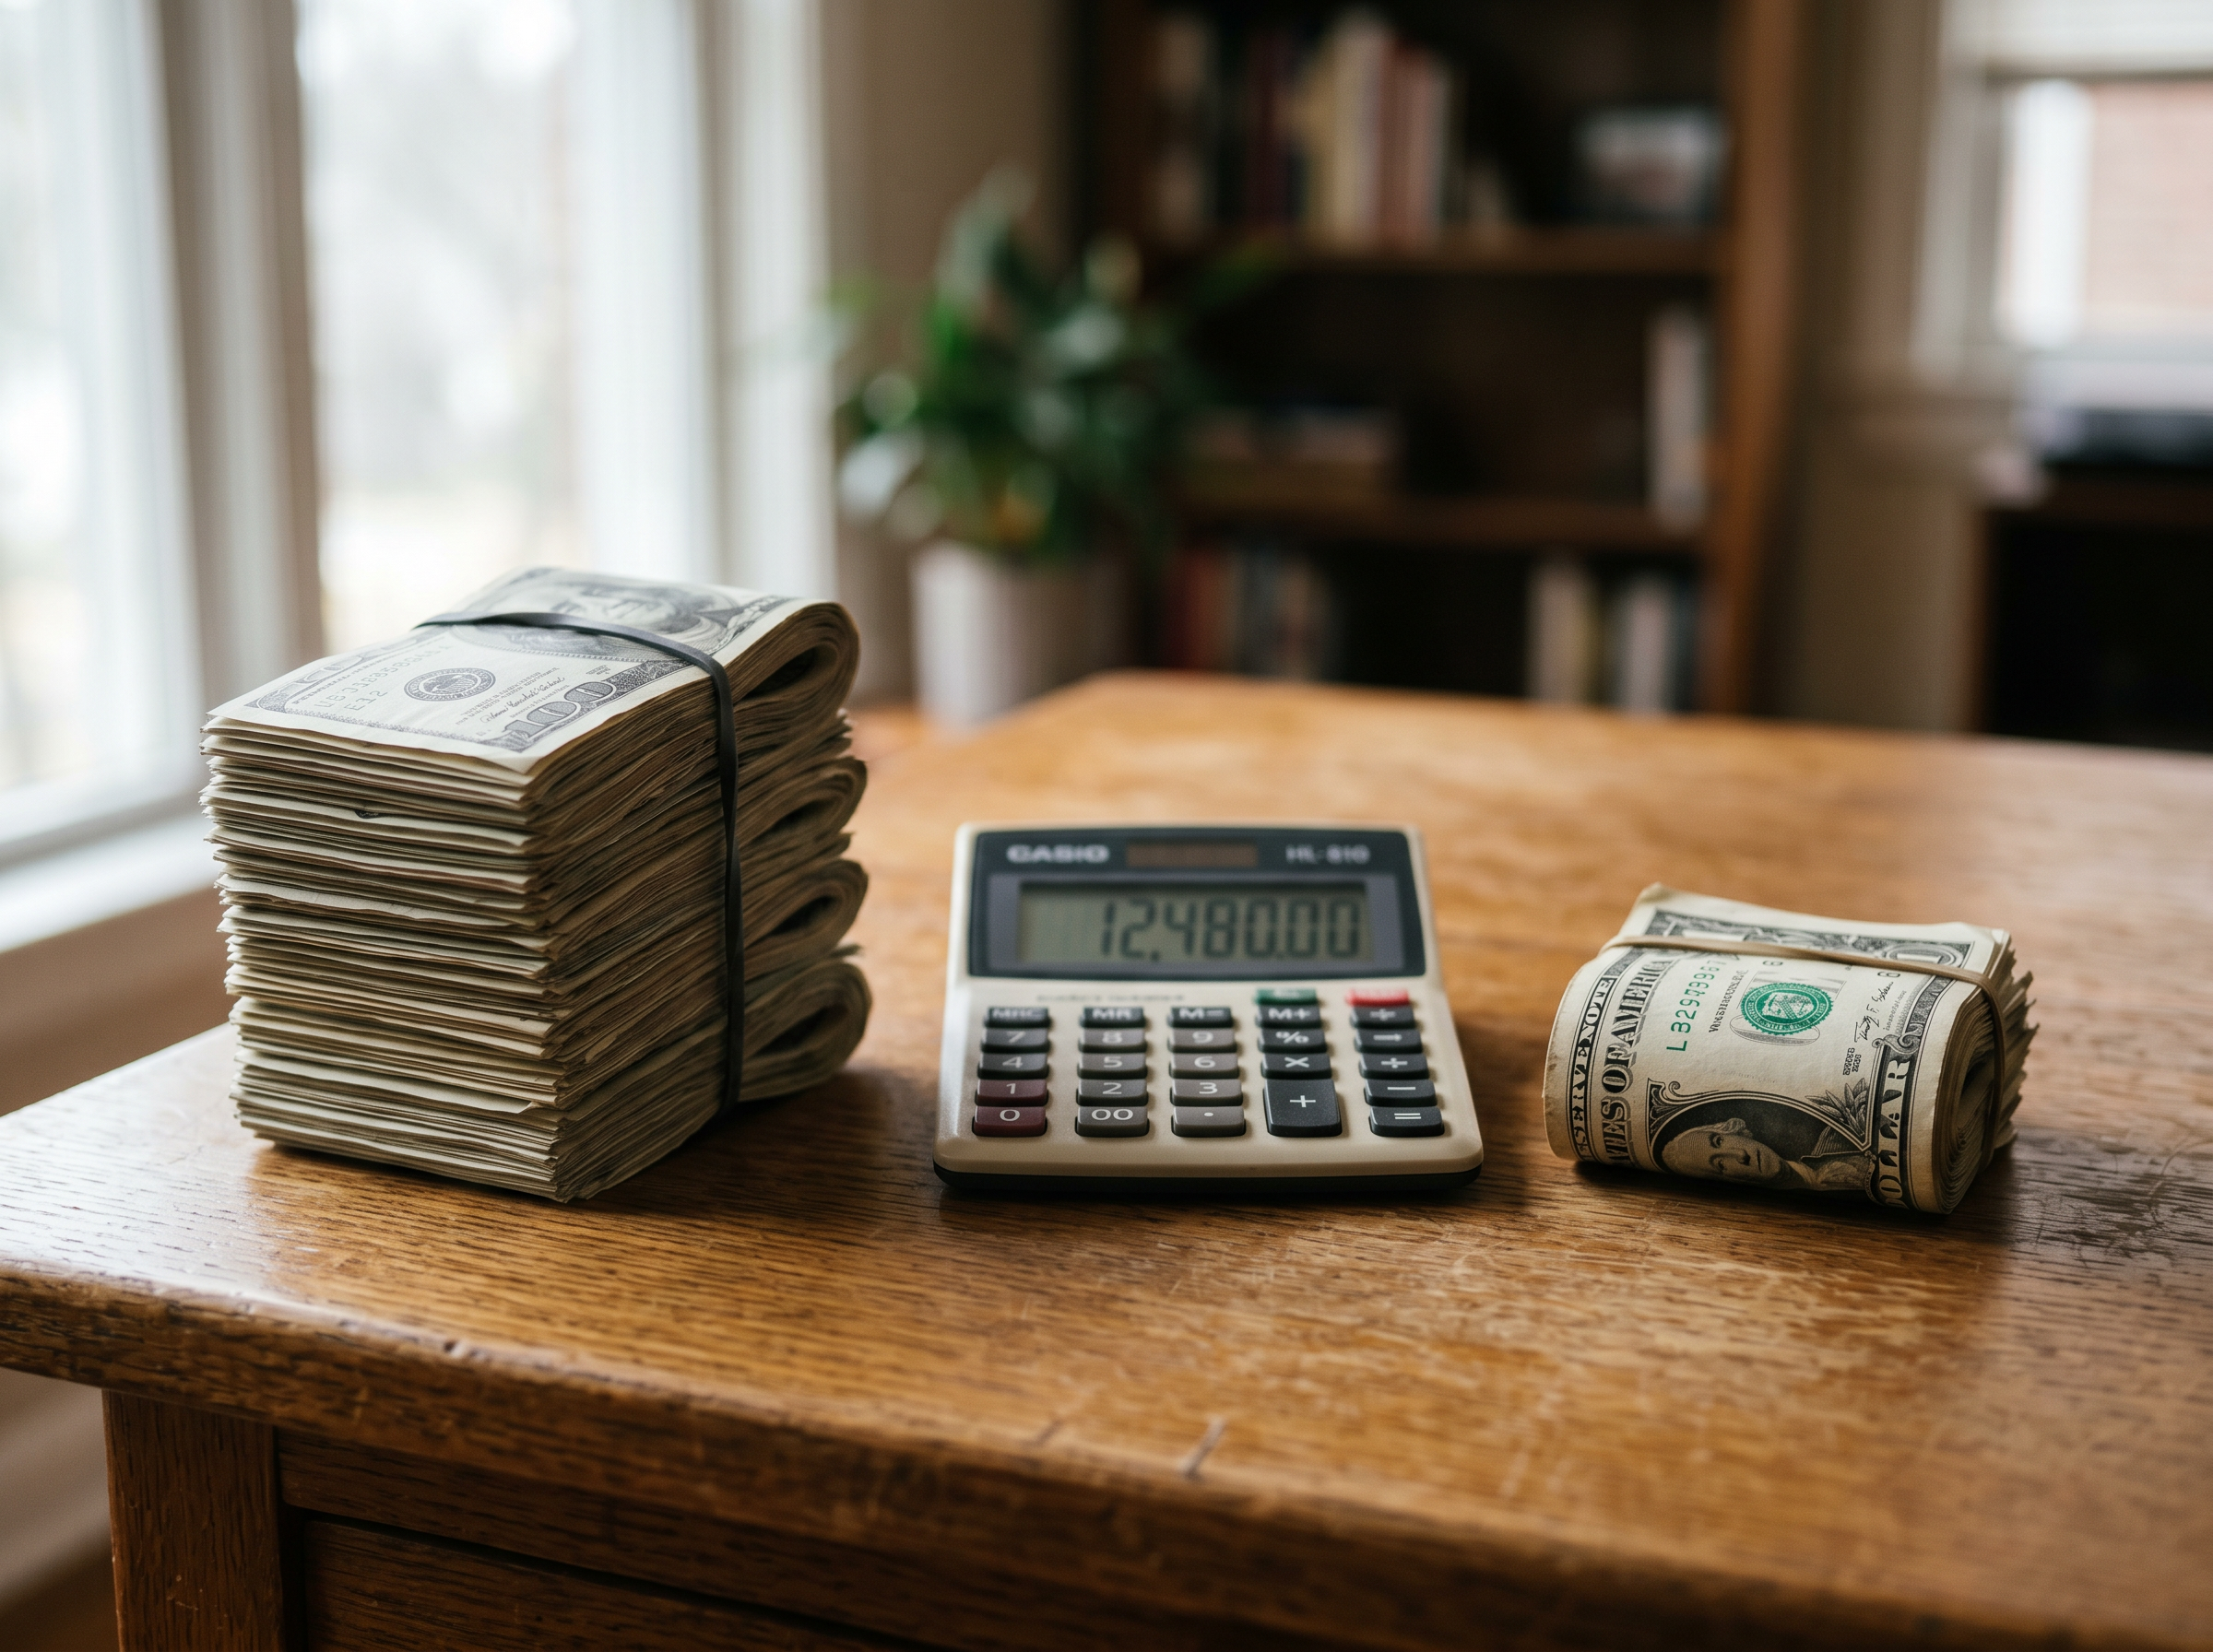 On paper, $80,000. After commissions, closing costs, and the mortgage payoff — closer to $60,000 in hand.
| Item | Amount | Description |
|---|---|---|
| Home Sale Price | $500,000 | The price the home sells for on the market. |
| Remaining Mortgage | -$340,000 | The outstanding loan balance that must be paid off. |
| Selling Costs (8%) | -$40,000 | Includes realtor commissions, closing costs, and other fees. |
| Net Proceeds | $120,000 | The total cash available for distribution. |
| David's Share (50%) | $60,000 | David's portion of the cash after all expenses. |
As the table illustrates, David’s $80,000 in equity does not translate to $80,000 in his pocket. After accounting for the costs of selling, his actual cash payout is $60,000. This 25% reduction is a stark reminder that equity on paper and cash in hand are two very different things. For co-owners, understanding this difference is not just good financial practice—it is essential for maintaining a healthy and transparent partnership. Keeping a clear and accurate account of each person’s stake using the co-ownership equity tracking guide is the best way to prevent misunderstandings and ensure that when the time comes to part ways, the conversation is based on reality, not illusion.
FAQ
What is the difference between home equity and cash?
Home equity is the portion of the property you own after subtracting the outstanding mortgage balance from the current market value. Cash is liquid money you can spend immediately. Equity is wealth locked inside an illiquid asset, which means the number on paper does not translate one-to-one into money in a bank account.
Why can't I just withdraw my home equity like a savings account?
Equity is tied to the physical asset of the home. To turn equity into cash, you have to either sell the property, refinance into a larger loan that extracts cash, or borrow against the equity through a HELOC. Each path has closing costs, fees, or new monthly payments, so none of them produce a clean one-for-one conversion.
How can co-owners convert equity into cash?
The three main options are selling the property and splitting net proceeds, refinancing with one co-owner cashing out to pay the other, or opening a HELOC against the shared equity. Selling is the most direct; refinancing leaves the remaining owner solely responsible for a larger loan; a HELOC adds a second monthly payment on top of the existing mortgage.
Why does equity on paper differ from cash at closing?
Selling a home costs money. Realtor commissions, closing costs, and other fees can easily take 7–10% of the sale price off the top, plus the mortgage must be paid off in full before anything is distributed. A co-owner with $80,000 of equity on paper may walk away with closer to $60,000 in actual cash once those costs are subtracted.
What are the ways equity can shrink?
Equity drops when the property loses market value, when capital improvements depreciate past their useful life, and when new debt is taken against the home (such as a HELOC or cash-out refinance) because that debt increases the amount owed. A falling market plus a growing loan balance can erase years of equity gains quickly.
Real Amigos is a tool to make co-ownership financial tracking simple, transparent, and automatic. Learn more about early access.